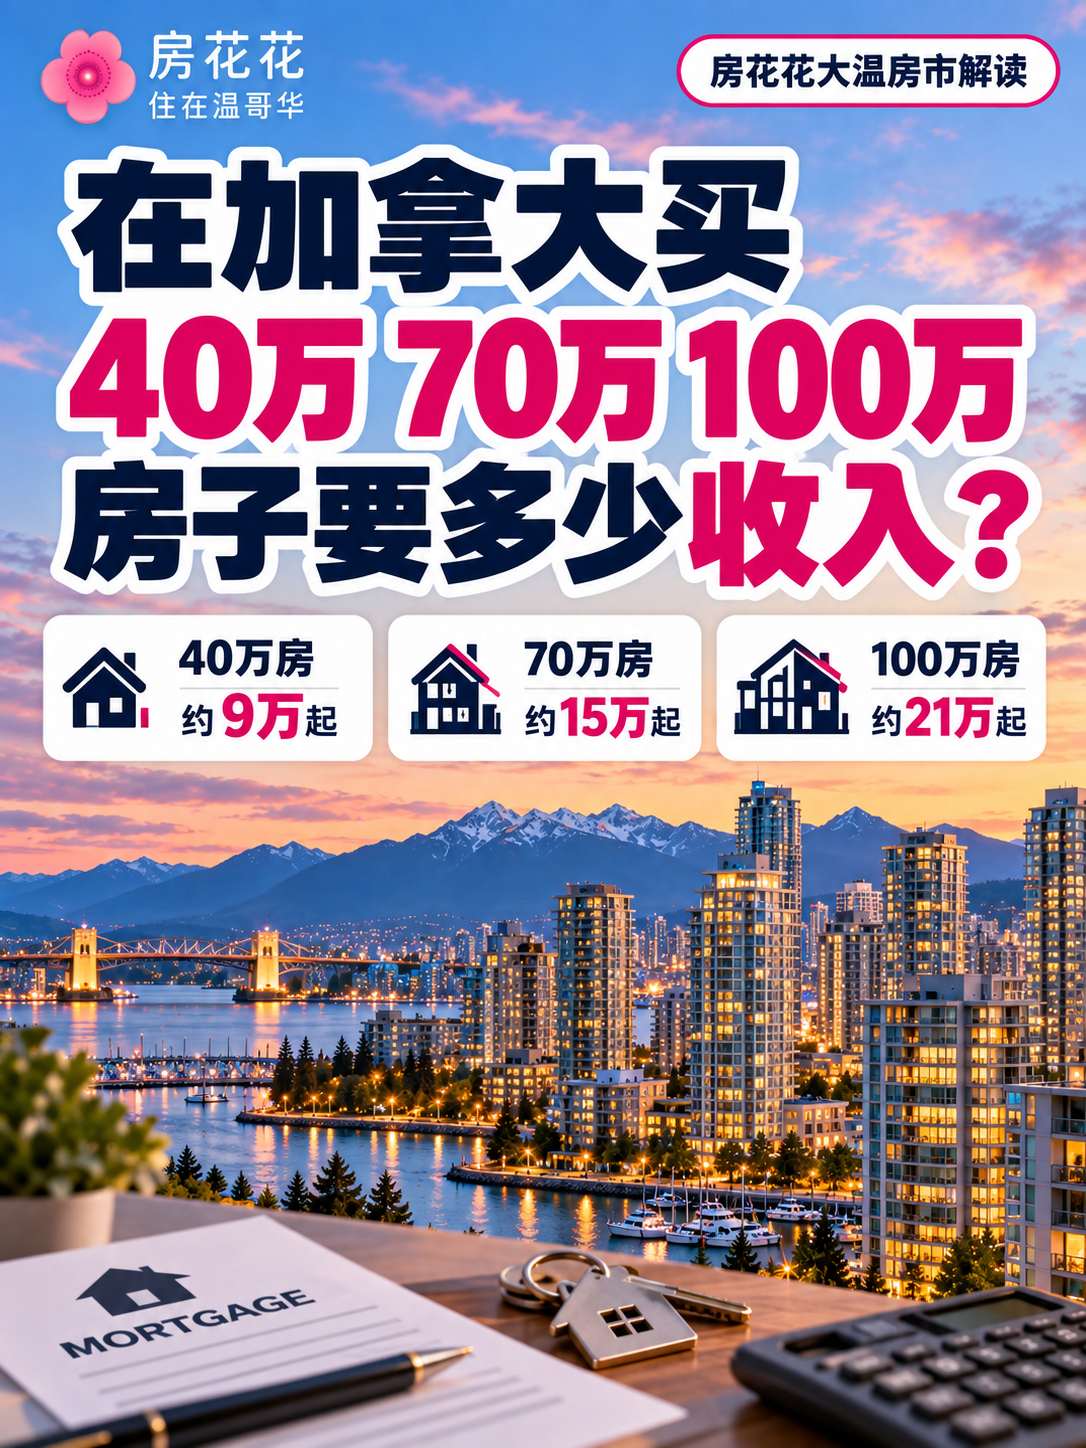
🏠 在加拿大买40万、70万、100万的房子,家庭年收入到底要多少?
💰 房价 $400,000
银行审批参考:家庭年收入约 $90,000
相对舒服:约 $105,000
💰 房价 $700,000
银行审批参考:家庭年收入约 $150,000
相对舒服:约 $175,000
💰 房价 $1,000,000
银行审批参考:家庭年收入约 $210,000
相对舒服:约 $245,000
.
📌 为什么银行批得下来,你还是可能觉得压力很大?
因为加拿大申请房贷,不是单纯用你拿到的实际利率计算。
银行还要做 Mortgage Stress Test 房贷压力测试:
按照5.25% 或合同利率+2%
两者取较高值来测试你的偿债能力。
同时,还会看住房相关支出占家庭总收入的比例,包括:
• 房贷月供
• 房产税
• 取暖费用
• 以及你的其他债务
所以收入刚刚踩着银行审批线买房,现实生活中往往会比较紧。
比如你家庭收入15万,银行可能允许你考虑70万左右的房子,但买完之后还有:
房屋保险、车贷、车险、吃饭、孩子、旅游、维修、Condo Fee以及日常储蓄……
真正能自由支配的钱,可能没有想象中那么多。
.
📌 所以更值得参考的是“舒适收入线”
理财规划师Christopher Liew给出的思路是:
住房成本最好控制在家庭总收入的 1/3左右,而且最好按照压力测试后的月供去做预算,而不是只看现在的优惠利率。
但我觉得,对于真正准备买房的人来说,这个数字反而更值得参考。
因为银行告诉你的是“最多可以买多少”,你真正应该考虑的是“买多少不会影响生活”。
⚠️ 不要把全部存款都拿去做首付。
律师费、土地转让税、搬家费、验房、保险,以及买房后的家具维修,都需要另外准备现金。
所以买房真正应该问的,从来不是:“银行最多能借我多少钱?”
而应该是:“这个价格的房子,我买完以后还能不能正常生活、存钱和应对利率变化?”
这两个答案,可能差几十万。
📌 建议准备买房的人先收藏,之后看房前把自己的家庭收入、首付和每月固定支出代进去算一遍。
 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.
Comments:
Post Your Comment: